


Sep 24, 2026 7:13 PM
Updated Sep 25, 2026 9:18 AM
Selected yields and key metrics as of the 24th September, 2026.
This article was originally published by Curve on Curve News.Curve this week in 60 seconds
- USD LP highlights: sUSG/reUSD (Re Protocol) 16.0% and frxUSD/sUSDai 14.0% APR.
- Lending: supply crvUSD against svZCHF gave a steady 5.7% APR.
- ETH LP highlights: ETH+/WETH at 6.0% modeled APR. This is ETH-yield, not dollar.
- crvUSD: scrvUSD showed 3.2% APY for savers and average mint borrowing cost was 3.7% APY.
- CRV holders: CRV/cvxCRV at 17.7% APR; direct veCRV voting rewards require a separate locked-CRV position.
- TricryptoUSDC: higher fee settings are live. Traders may pay more, with the DAO expected to earn more as a result.
Selected yields
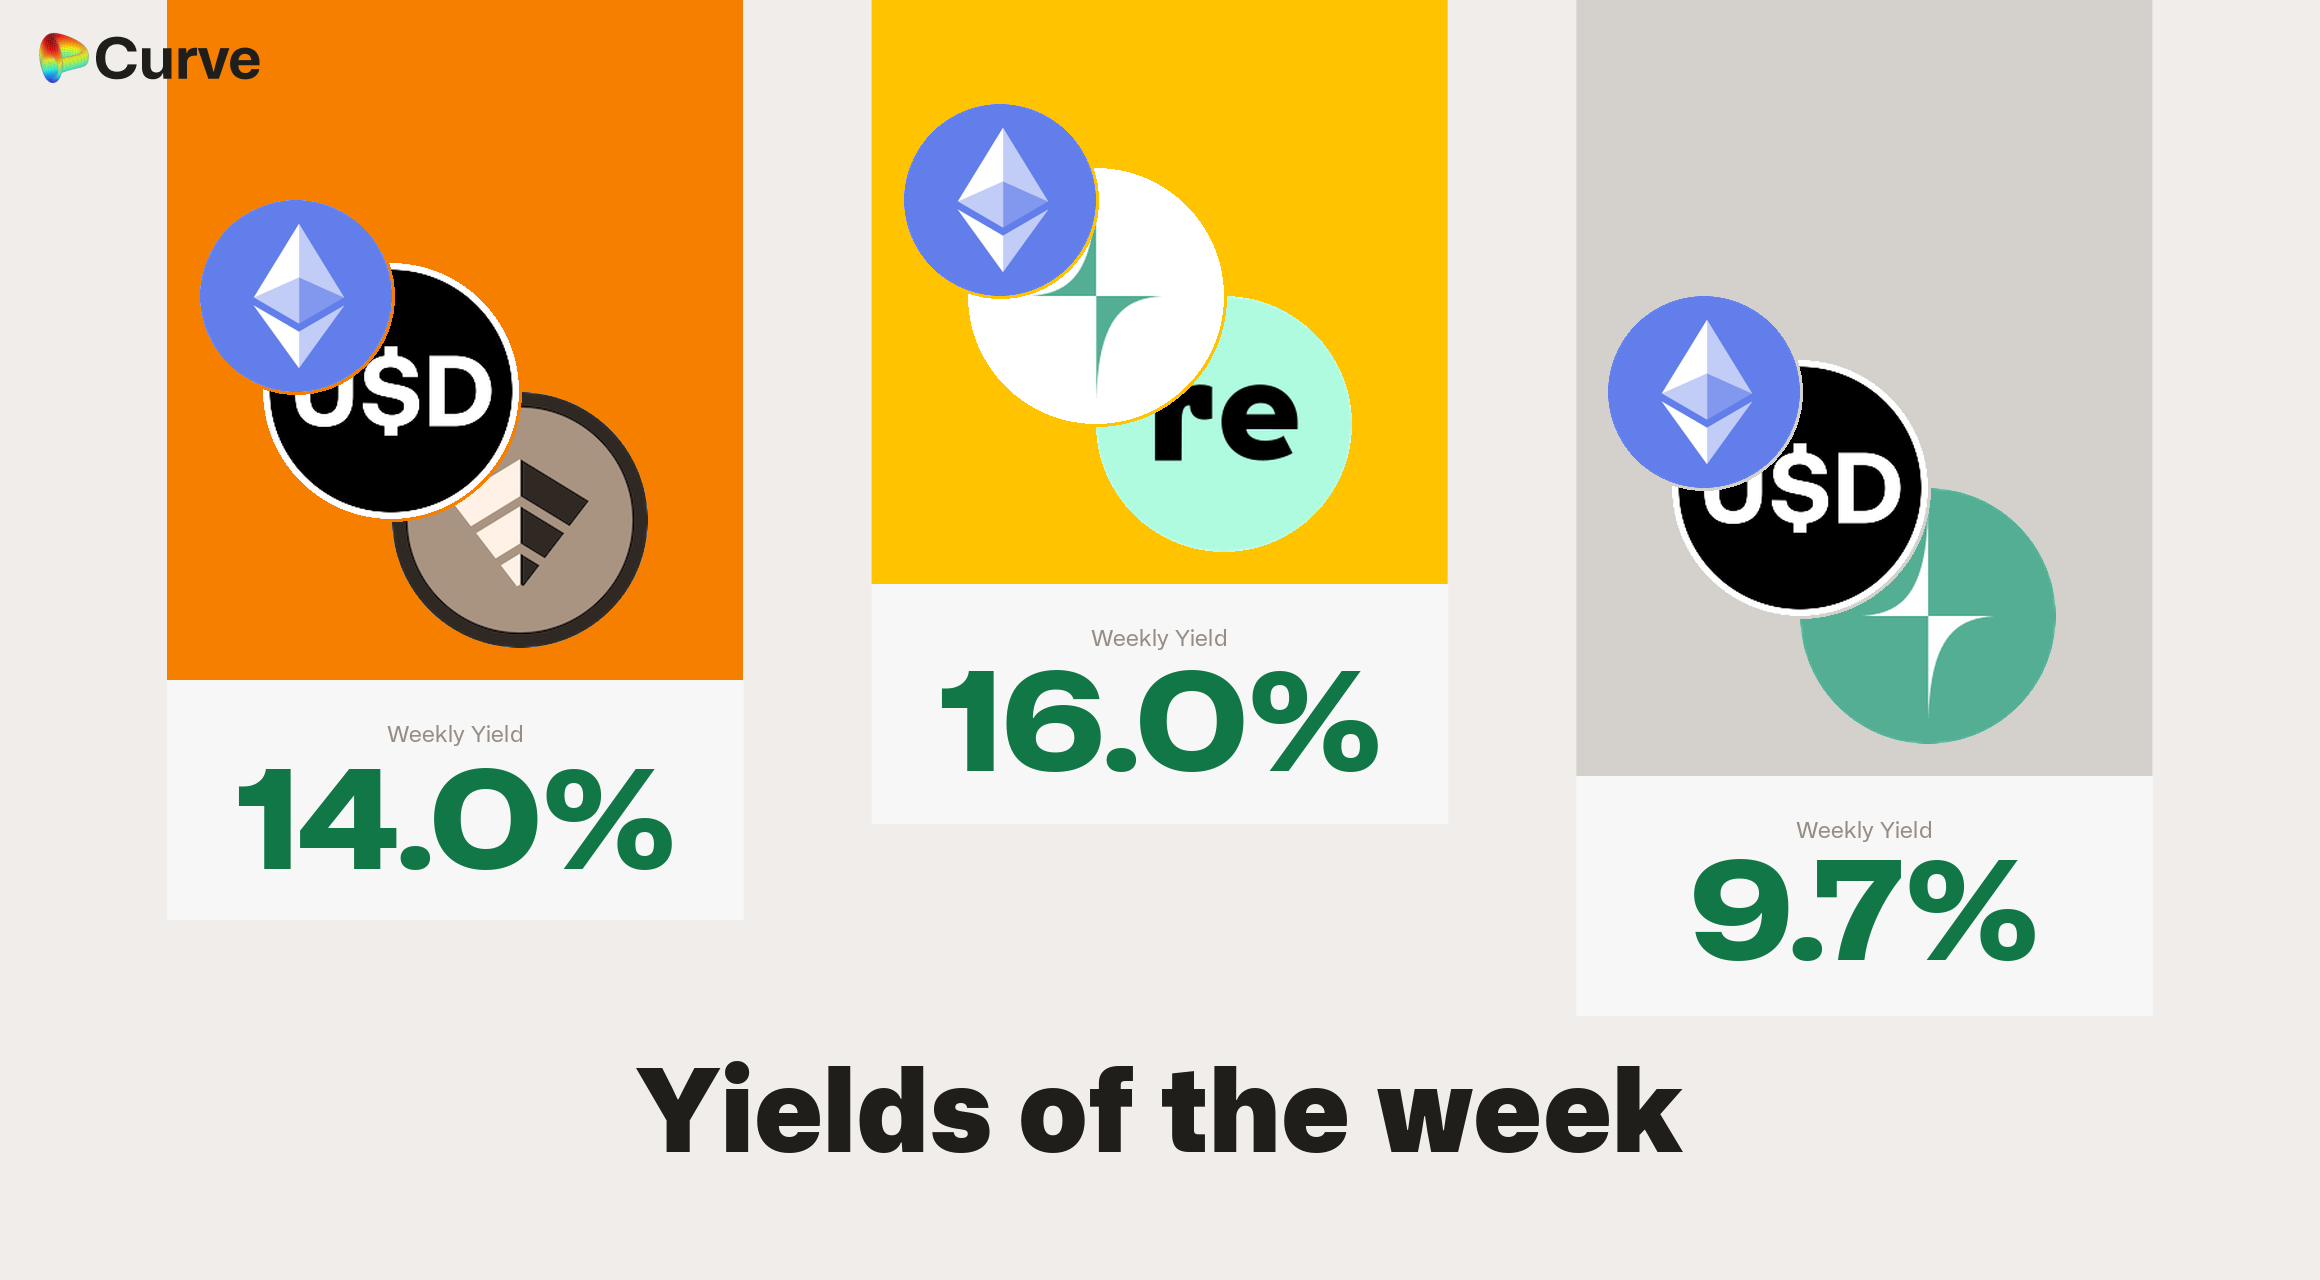 Curve Selected Yields & Key Metrics: Week 39, 2026
Markets shown have at least $100,000 in pool liquidity or supplied assets. Pool APRs model a new $100,000 deposit using seven-day LP growth and current unboosted rewards at unchanged income. Actual rates are variable; these are selected candidates, not a global top-yield or risk ranking. CRV rewards can be boosted via Convex, StakeDAO or Yearn.
Selected USD yields
| Chain | Market | APR |
|---|---|---|
 |  sUSG  reUSD (Re Protocol) | 16.0% |
|  frxUSD  sUSDai | 14.0% |
| frxUSD  USG | 9.7% |
| frxUSD  USD3 | 9.3% |
|  sUSDx  USDx | 9.2% |
| USG  sDOLA | 9.1% |
 |  frxUSD  FXB20551231 | 8.5% |
|  USDC USG | 7.7% |
|  fxUSD frxUSD | 7.2% |
|  scrvUSD sDOLA | 6.4% |
Re Protocol reUSD is a reinsurance share: minting is KYC-gated for eligible non-U.S. users, and direct redemptions are capped or queued. USD.AI says sUSDai is not a stablecoin; issuer unstaking uses a 30-day FIFO epoch and can take longer when liquidity is tight. Pool exits depend on liquidity, not just the APR.
Selected Llamalend supply yields
 svZCHF
 sUSDe
 sfrxUSD (v2)
 syrupUSDC
 wstETH
 sreUSD

 USDC
 wstETH
Lending APR may include borrower interest and CRV rewards.
Selected BTC and ETH yields
| Chain | Market | Asset | APR |
|---|---|---|---|
|  ETH+  WETH | ETH | 6.0% |
|  WBTC  cbBTC  hemiBTC | BTC | 2.7% |
|  tETH  weETH | ETH | 2.3% |
| WETH weETH | ETH | 2.0% |
|  ETH  ETHx | ETH | 1.9% |
|  stETH  frxETH | ETH | 1.6% |
Other selected yields
| Chain | Market | Asset | APR |
|---|---|---|---|
|  CRV  cvxCRV | CRV | 17.7% |
| CRV  sdCRV | CRV | 12.0% |
| CRV cvxCRV | CRV | 8.5% |
|  crvUSD WETH CRV | TRICRYPTO | 6.6% |
| crvUSD  ZCHF | FOREX | 4.6% |
|  GHO cbBTC WETH | TRICRYPTO | 4.1% |
| USDC WBTC WETH | TRICRYPTO | 2.5% |
Protocol activity and stability
Borrowers did not simply pile into leveraged ETH longs. One notable crvUSD mint-market borrower pledged 100 cbBTC for a 5 million crvUSD loan at 3.60% interest.
crvUSD & scrvUSD
| Metric | Value | Weekly change |
|---|---|---|
| Mint-market debt | $77.4M | +5.6% |
 scrvUSD yield (APY) | 3.2% | -0.1 pp |
| scrvUSD assets / mint debt | 20.8% | -0.9 pp |
| crvUSD oracle price | $0.9999 | +$0.0001 |
| Average borrow APY | 3.7% | +0.1 pp |
| PegKeeper debt | 22.70M crvUSD | +14.87M crvUSD |
| Mint borrowing fees collected | $52.2k | +20.0% |
Balances and rates use Thursday noon UTC; completed-week mint-fee activity ends Thursday 00:00 UTC. Weekly changes compare like-for-like observations.
Average borrow APY is weighted by debt across mint markets. Your borrowing rate depends on the market and collateral you use.
Llamalend
| Metric | Value | Weekly change |
|---|---|---|
| Llamalend TVL | $272M | +8.1% |
| Supplied | $94M | -0.1% |
| Borrowed | $148M | +4.4% |
| Collateral | $248M | +10.0% |
| Loans | 1,178 | +13 |
| V2 accrued admin fees | $1.7k | +1.1% |
TVL counts lending and mint markets; supplied assets is lending-only. V2 admin fees are accrued, not cash collected.
DAO
| Metric | Value | Weekly change |
|---|---|---|
 veCRV distribution | $116.2k | +27.1% |
| veCRV APR | 2.357% | +0.414 pp |
| CRV emissions (weekly gauge allocation) | 1.83M CRV ($606.2k) | -1.51% |
| Annual CRV inflation | 4.014% | -0.003 pp |
Governance and protocol updates
TricryptoUSDC's higher-fee trade-off is live
The analysis behind the change modeled more than twice the swap fees despite about 46% less volume: higher average fees outweighed fewer trades. The fee change is now applied and the pool-parameter ramp is complete. Traders may pay more; actual LP and DAO revenue is expected to increase for this pool.
Vote incentives campaigns
veCRV holders can compare two direct voting campaigns for the next allocation: alETH/frxETH has a shared 900 ALCX budget, and HemiBTC/cbBTC/WBTC about 1,851 USDC.
Explore Curve
Explore Curve pools, Llamalend markets or savings crvUSD. Choose the product that fits the asset and liquidity you need.
Risk information: pool risks, lending risks and crvUSD risks.
Comments

Powered by RoundtableBuilt on infrastructure designed for real-time media. Learn more at RTB.io.© Roundtable 2026. By using this site you agree to the Terms of Use and Privacy Policy